Payroll, Article 21 Income Tax, and BPJS with an HRIS: From Spreadsheets to an Auditable System
In this article
- Summary
- The problems with spreadsheet-based payroll
- Earnings and deduction components calculated
- Income tax and BPJS: what to configure
- A disciplined monthly payroll flow
- Integration with attendance, leave, and scheduling
- Security and control of payroll data
- Moving from spreadsheets to a system
- Indicators of success
- Frequently asked questions
- Conclusion
Payroll is one of the processes a company can least afford to get wrong. Employees judge a company's professionalism by the accuracy of their pay and payslip, while the state judges compliance by the accuracy of tax withholding and social security contributions. Yet in many growing businesses, payroll is still calculated in a spreadsheet whose formulas were inherited from a predecessor, with attendance, overtime, and allowance data gathered manually from many sources.
This article covers how an HRIS handles payroll in Indonesia: the components calculated, the monthly workflow, handling of Article 21 income tax and BPJS contributions, controls to prevent errors and fraud, and how to move from spreadsheets to a system safely. The discussion is general and does not replace advice from a tax or labor consultant, since rates and limits can change with regulation.
Summary
- Reliable payroll depends on clean input data: attendance, overtime, leave, allowances, deductions, and consistent employee personal data
- The system calculates gross pay, income tax withholding, BPJS contributions, and other deductions from configured rules, not formulas scattered across spreadsheets
- A disciplined monthly flow, from data cutoff and preview through approval to payment and reporting, reduces errors and HR overtime
- Segregation of duties, audit trails, and restricted access protect highly sensitive salary data
- Transition in stages: run in parallel for one or two cycles with the old method before the system becomes the source of truth
The problems with spreadsheet-based payroll
Spreadsheets are flexible, which is why they last so long. But a recurring pattern of problems appears in businesses that grow past a few dozen employees.
- Fragile formulas: one overwritten cell changes the results of many employees without anyone noticing
- Scattered data: attendance from machines or apps, overtime from supervisor approvals, and allowances from verbal agreements must be combined manually every month
- Dependence on one person: only one staff member understands the calculation logic
- Regulatory change: when tax rates or methods change, every formula must be updated and retested
- Weak confidentiality: salary files circulate by email and chat with little control over who sees them
- Hard to audit: it is unclear who changed what figure and when
- Wasted time: the HR team spends days at the end of each month, and near payday every correction becomes pressure
The classic symptoms are employee complaints about payslip discrepancies, corrections the following month, and worry during tax examinations. When these appear, the quiet cost of the old way already exceeds the cost of a system.
Earnings and deduction components calculated
A good payroll system models pay components as configurable data, not numbers retyped every month.
Earnings
- Base salary and fixed allowances, such as a position allowance
- Variable allowances tied to attendance, such as daily meal and transport allowances
- Overtime, calculated from attendance data and applicable rules, as discussed in [overtime calculation in HR systems](/blog/perhitungan-lembur-di-sistem-hr)
- Commissions and incentives, sourced from sales data or performance results
- Bonuses and holiday allowances paid at certain times
- Reimbursements, coming from the process of [employee reimbursement and travel expenses](/blog/reimbursement-dan-pengelolaan-biaya-perjalanan-karyawan)
Deductions
- Article 21 income tax
- The employee portion of BPJS Kesehatan and BPJS Ketenagakerjaan contributions
- Employee loans or advances repaid in installments
- Late arrival or absence deductions per company policy
- Other agreed deductions, such as cooperative contributions
Employer costs
Besides what is deducted from employees, part of the contributions is borne by the company. This value does not appear as a deduction on the payslip but must enter labor cost calculations and accounting journals.
Income tax and BPJS: what to configure
These two areas cause the most errors because the rules are layered and change over time.
Article 21 income tax
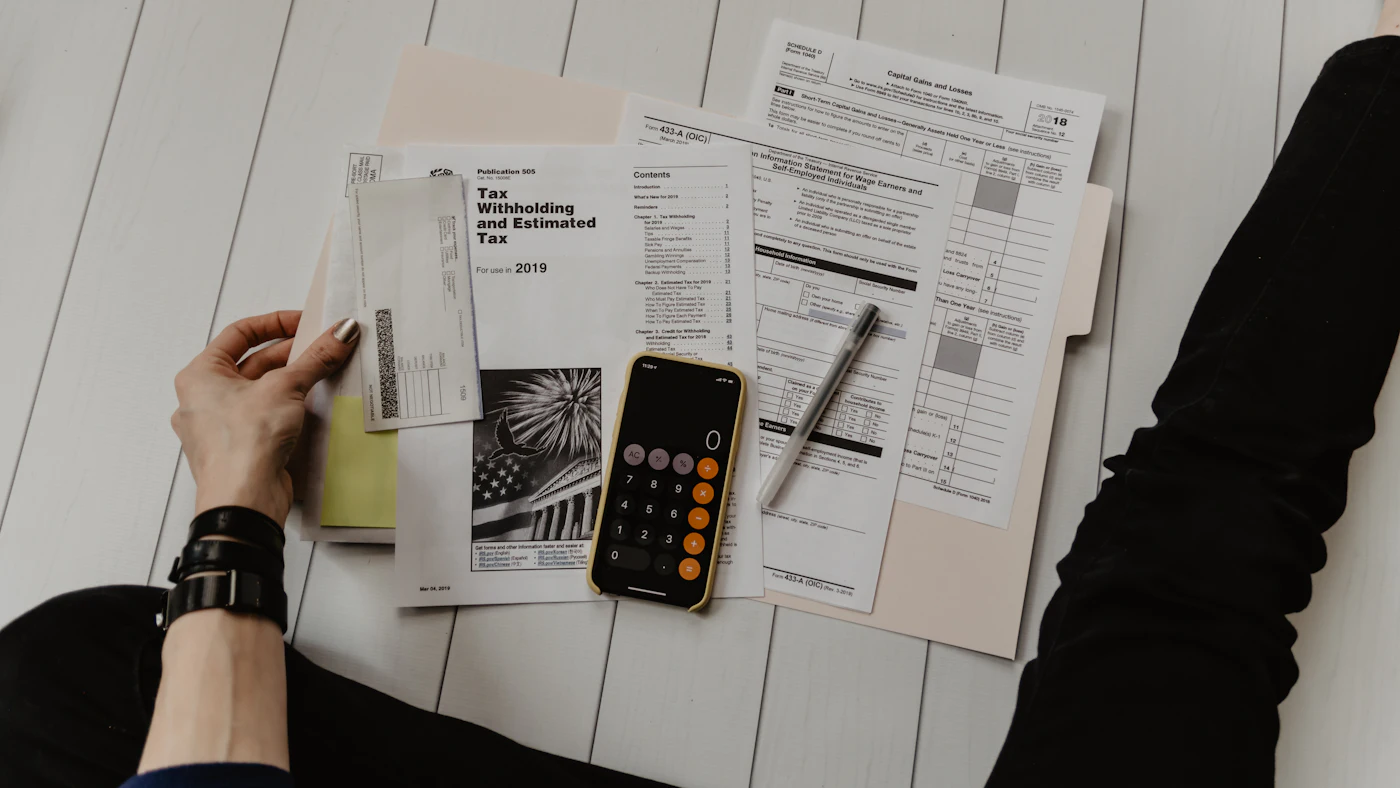
The system must store the data that determines the calculation, such as the employee's tax status, tax identification number, and year-to-date income. Since early 2024, monthly withholding has generally used an average effective rate based on categories, with an adjustment in the final tax period to compute the actual annual tax. Because the method differs between ordinary and final tax periods, the system should handle both and keep a history of calculations. Confirm the latest provisions with a tax consultant or official sources.
A good system also helps prepare withholding slips and reporting data so year-end work does not become a separate manual project.
BPJS contributions
BPJS Kesehatan and BPJS Ketenagakerjaan, which covers programs such as old-age security, pension, work accident, and death benefits, have contribution percentages and wage caps set by regulation that can change. Configure the percentages and caps as parameters with effective dates, not numbers embedded in formulas. That way a change is made once without touching the calculation logic, and last month's calculation still uses the parameters in force at the time.
Also make sure membership data, such as membership numbers and number of dependents, is stored neatly in the employee record.
A disciplined monthly payroll flow
Payroll errors usually come from a loose workflow, not from formulas. The flow below can be adapted to company size.
- Data cutoff: set a deadline for attendance, overtime, leave, and employee data changes. Data after the cutoff is processed in the next cycle unless specially approved
- Input verification: check exceptions, such as employees without attendance data, overtime above the limit, and employees who joined or left mid-month
- Calculate and review a preview: the system produces an initial calculation and HR compares it with last month. Large differences per employee or in total are investigated before continuing
- Tiered approval: an HR or finance superior approves the total, not just the person who prepared the calculation
- Payment: the bulk transfer file is generated from approved data rather than retyped, and matched through [bank reconciliation](/blog/rekonsiliasi-bank-otomatis-dengan-erp)
- Payslip distribution: payslips are sent through a secure employee portal, not widely circulating email attachments
- Reporting and journals: tax, contributions, and salary expense are journaled to accounting, and reporting data is prepared
- Period locking: once complete, the period is locked; corrections are made as adjustments next month with a note
A preview compared with last month is the cheapest and most effective control. Many errors, such as an employee whose pay doubled or went to zero, are immediately visible at this stage.
Integration with attendance, leave, and scheduling
Payroll is only as good as the data going into it. That makes integration with other modules decisive for accuracy.
- Attendance: attendance data from machines, apps, or field locations underpins daily deductions and allowances. For field teams, see [managing field employee attendance](/blog/mengelola-absensi-karyawan-lapangan)
- Leave: paid and unpaid leave types affect the calculation, so approved leave status must flow automatically
- Shifts and overtime: for businesses with rotating work patterns, schedules determine shift allowances and overtime, as in [shift scheduling and workforce management](/blog/penjadwalan-shift-dan-manajemen-tenaga-kerja)
- Performance and commission: sales and target data flow into incentives
- Accounting: salary expense and tax and contribution liabilities are journaled automatically
With a self-service portal, employees can view payslips, remaining leave, and request corrections themselves, reducing the question load on HR. The benefits are covered in employee self-service.
Security and control of payroll data
Salary data is among the most sensitive information in a company, so its controls need to be serious.
- Role-based access: only payroll staff can view and change salaries; a direct supervisor is not automatically allowed to see the whole team's pay
- Segregation of duties: the person who changes salary master data is not the person who approves payment
- Audit trail: every change to salary, allowance, or employee bank account is recorded with who, when, and the values before and after, in line with [audit trails and internal controls](/blog/jejak-audit-dan-pengendalian-internal-di-sistem-erp)
- Personal data protection: identity numbers, accounts, and family data are protected per [employee personal data security](/blog/menjaga-keamanan-data-pribadi-karyawan)
- Bank account change verification: because account changes are a common fraud method, require additional verification before a new account is used
- Backup and recovery: payroll data must be covered by the data backup strategy
A classic fraud pattern is a fictitious employee, or a former employee who still receives pay. Routine matching between the active employee list, attendance, and transfer recipients will expose it.
Moving from spreadsheets to a system
Switching payroll should be done carefully because errors are felt immediately by all employees.
- Map every pay component and special rule that has lived in the spreadsheet, including unwritten habits
- Clean employee data: names matching documents, tax numbers, status, bank accounts, and BPJS membership
- Configure components, tax, and contributions, then test with past months' data and compare with old results
- Run in parallel for one or two cycles: calculate in the system and in the old way, investigate every difference, and decide which is correct
- Train the HR team and explain the changes to employees, especially the new payslip format
- Set the switch date just after payday, not just before, and prepare a fallback plan
- After the switch, review a full month of results before retiring the old way completely
Mistakes that often occur at this stage are reviewed in common HRIS implementation mistakes, such as migrating unclean data or skipping the parallel run.
Indicators of success
- Number of payroll corrections per month, ideally falling
- Processing time from data cutoff to payment
- Number of employee complaints about payslips
- Timeliness of payment and of tax and contribution reporting
- Number of exceptions found at the preview stage
- Percentage of employees using the self-service portal
Frequently asked questions
Does a small business with ten employees need a payroll system?
Not necessarily a big system, but it still needs consistent rules and tidy data. Once there is overtime, several kinds of allowances, or employees joining and leaving through the year, automation starts saving time and reducing risk, especially for tax and contributions.
What if tax or contribution rules change?
That is why parameters must be settable with effective dates. The change is configured once, tested with examples, and applies only to the right period without altering past calculations. Still confirm the interpretation with a tax consultant.
Can payslips be sent by ordinary email?
It is best avoided. Use a portal that requires login, or at least password-protected files. Payslips hold sensitive data, and a misdirected email can become a data leak incident.
How are employees who join or leave mid-month handled?
The system needs to support proration based on working days or calendar days per policy, plus special handling of tax and contributions in the months of joining and leaving. Test these cases specifically before switching.
Must payroll connect to accounting?
Strongly recommended. Without integration, salary expense, tax liabilities, and contribution liabilities have to be journaled manually and are prone to discrepancies. Integration also makes reconciliation with bank transfers easier.
Conclusion
Good payroll is not the product of clever formulas but of clean input data, properly configured tax and contribution parameters, a disciplined monthly flow, and controls that protect sensitive data. An HRIS brings it all together so HR can move from recalculating to reviewing exceptions, and employees receive accurate pay on time with a clear payslip.
Agsora helps companies implement an HRIS and payroll that fit your policies, from mapping pay components and integrating attendance to parallel testing before the switch. If your payroll still depends on spreadsheets, let us discuss the first step.
Tidy up payroll with an HRIS
Agsora helps implement an HRIS and payroll integrated with attendance, leave, and accounting according to your company policies.
Free ConsultationRecommended for you
Reading related to this topic
Recruitment and Applicant Tracking Systems for a Growing Business
When a business needs an ATS, its core functions, designing a fair hiring flow, protecting candidate experience, applicant data protection, and choosing the right system.
Shift Scheduling and Workforce Management: Fair Schedules, Controlled Costs
Building work schedules from service needs: fair and lawful rules, employee availability, shift swaps, links to attendance and payroll, labour cost, and retention.
Project and Milestone Billing for Service Businesses: Keeping Cash Flow and Margin Healthy
Designing healthy project billing: choosing a model, milestones with acceptance criteria, schedules aligned with cash flow, scope changes, time recording, and revenue recognition.
Free checklist: choosing a software house
24 points to evaluate a vendor before you sign. Can be saved as a PDF.
Ready to build a system that grows with your business?
Discuss your needs with the AG·SORA team, no cost, no commitment.